


MARYLAND FORECLOSURE PREVENTION & PRE-FORECLOSURE HELP
Behind on Your Mortgage in Maryland? You May Have More Options Than You Think.
If you've fallen behind on mortgage payments, received a Notice of Intent to Foreclose, or are worried about losing your home, it's important to understand where you stand and what options may still be available.
I'm Dan McDevitt, a Maryland Realtor with more than 20 years of real estate experience and over 150 short sale transactions. I help homeowners evaluate their real estate options when mortgage difficulties, foreclosure concerns, or financial hardship make the next step uncertain.
Being behind on your mortgage doesn't automatically mean foreclosure is inevitable. What matters now is understanding your situation and taking the appropriate next step.
Sometimes the best solution is working with your mortgage lender. Sometimes it's speaking with a housing counselor, foreclosure attorney, or bankruptcy attorney about ways to protect your home. And sometimes selling the property, whether through a traditional sale or a short sale, may be the most practical option.
My goal isn't to pressure you into selling. It's to help you understand your real estate options, answer your questions honestly, and help you determine what makes the most sense for your circumstances.
Schedule a Free, Confidential Conversation With DanPrefer to speak directly? Call or Text 410-670-4762
No pressure. No obligation. Just an honest conversation about your options.
Important: Facing an Upcoming Foreclosure Sale?
If you've received foreclosure notices or have an upcoming auction date, don't wait to seek assistance. Contact your mortgage servicer promptly and consider speaking with a HUD-approved housing counselor, a Maryland foreclosure attorney, or an experienced bankruptcy attorney.
Bankruptcy may be an option worth exploring. Filing bankruptcy generally triggers an automatic stay that can temporarily stop foreclosure proceedings, including an upcoming foreclosure sale. However, exceptions and limitations apply, and bankruptcy does not guarantee that you can keep your home. An experienced bankruptcy attorney can explain whether Chapter 7 or Chapter 13 may be appropriate for your situation.
Dan McDevitt is a licensed real estate professional, not an attorney or housing counselor. This information is educational and is not legal, bankruptcy, or financial advice. Consulting with a Realtor does not pause or stop foreclosure proceedings.
UNDERSTANDING YOUR SITUATION
Where Are You in the Foreclosure Process?
Every homeowner's situation is different. Whether you've missed your first mortgage payment or already have a foreclosure sale scheduled, understanding where you stand is an important first step toward determining what options may still be available.
SITUATION 01
Behind on Your Mortgage Payments
Maybe you've missed one or two payments because of a job loss, unexpected expenses, illness, divorce, or another financial setback. You may be receiving calls or letters from your mortgage company and wondering how serious the situation has become.
What matters now: Contact your mortgage servicer as early as possible. Depending on your circumstances, repayment arrangements, forbearance, loan modification, or other loss-mitigation options may be available.
SITUATION 02
Received a Notice of Intent to Foreclose
Receiving a Notice of Intent to Foreclose can be frightening. In Maryland, this notice generally comes before the lender initiates a foreclosure case. It is a warning that the mortgage delinquency needs attention, but it does not mean your home has already been sold.
What matters now: Review the notice carefully, keep track of important dates, and explore your options promptly. This may be an important time to consult a housing counselor, attorney, or experienced real estate professional.
SITUATION 03
Foreclosure Proceedings Have Started
If you've received foreclosure court documents or an Order to Docket, the lender may have formally initiated the foreclosure process. That doesn't necessarily mean all options are gone, but the situation has become more time-sensitive.
What matters now: Speak with a qualified Maryland foreclosure attorney or housing counselor about your rights and deadlines. If selling is being considered, it's important to evaluate the home's value, mortgage balance, and available time.
SITUATION 04
A Foreclosure Auction Is Scheduled
If your home has a scheduled foreclosure auction, time is especially important. Depending on your situation, there may still be options worth exploring, but not every solution can be completed before the scheduled sale.
What matters now: Contact a Maryland foreclosure attorney or bankruptcy attorney immediately to discuss any available legal protections. A bankruptcy filing may temporarily stop a foreclosure sale through the automatic stay, subject to exceptions and limitations. Do not assume that listing your home for sale will postpone the auction.
You Don't Have to Make These Decisions Without Information.
Some homeowners are able to work out an arrangement with their lender and keep their home. Others may benefit from consulting a bankruptcy attorney about their legal options. And for some, selling the property before foreclosure may help them move forward with greater control over the outcome. The right path depends on your financial situation, your mortgage, and how much time you have.
KNOW THE PROCESS. UNDERSTAND YOUR OPTIONS.
How Does Foreclosure Work in Maryland?
Maryland has a legal foreclosure process with required notices, court filings, and opportunities for eligible homeowners to explore alternatives. Understanding the different stages can help you recognize what documents you've received, what deadlines may apply, and why taking action early is so important.
Missed Mortgage Payments
The process usually begins when a homeowner falls behind on mortgage payments. The mortgage servicer may begin contacting the homeowner, sending delinquency notices, and providing information about available mortgage assistance programs.
Why this matters: This is often the best time to contact your servicer about repayment arrangements, forbearance, loan modifications, or other potential solutions before foreclosure proceedings begin.
Notice of Intent to Foreclose (NOI)
Before filing a residential mortgage foreclosure action in Maryland, the lender generally must send a Notice of Intent to Foreclose at least 45 days before the court filing. The notice identifies the mortgage delinquency and provides information about the foreclosure process and possible assistance.
Important distinction: Receiving a Notice of Intent does not mean your house has been foreclosed on or sold. However, it is a serious warning that deserves immediate attention.
Order to Docket — Foreclosure Filed in Court
If the delinquency remains unresolved, the lender may file an Order to Docket or other applicable foreclosure filing in the Circuit Court where the property is located. This formally begins the court foreclosure case.
Under Maryland's general residential mortgage foreclosure rules, the filing cannot occur until at least 90 days after default and 45 days after the Notice of Intent was sent. For most federally covered mortgages, additional federal rules generally prevent the first foreclosure filing until the borrower is more than 120 days delinquent, subject to exceptions.
Why this matters: An Order to Docket is a major development, but it does not mean the property has already been sold. Homeowners should promptly review their legal rights, mortgage assistance options, and any remaining opportunities to resolve the situation.
Loss Mitigation Review & Foreclosure Mediation
During the foreclosure process, the mortgage servicer may evaluate the homeowner for alternatives to foreclosure, commonly called loss mitigation. These may include loan modifications, repayment arrangements, or other available programs.
Eligible Maryland homeowners may also have the right to request foreclosure mediation. Mediation provides an opportunity to meet with the mortgage servicer and a neutral administrative law judge to discuss potential alternatives.
Watch your deadlines: Eligible homeowners generally have 25 days from the applicable final loss mitigation affidavit notice to request postfile foreclosure mediation. Review the documents carefully and seek legal or housing counseling assistance promptly. Mediation does not guarantee an agreement.
Foreclosure Auction & Court Ratification
If the foreclosure is not resolved, the property may be scheduled for a public foreclosure auction. The lender must provide required notices, and the homeowner may still have certain rights or legal remedies depending on the circumstances and timing.
Following the auction, the sale generally must go through court ratification before title transfers to the purchaser. Homeowners should not assume that the time between auction and ratification gives them another ordinary opportunity to sell the property or undo the foreclosure.
Why this matters: If an auction is scheduled, contact a qualified foreclosure attorney or bankruptcy attorney immediately. Legal options may exist, but waiting until the last minute can severely limit what is possible.
How Long Does Foreclosure Take in Maryland?
There is no single foreclosure timeline that applies to every Maryland homeowner. The length of the process depends on the mortgage, applicable state and federal requirements, court proceedings, loss mitigation reviews, mediation, and whether a sale is postponed or challenged.
Rather than assuming you have a certain number of months, review the actual notices and court documents associated with your property. If you are considering selling, the amount of time remaining can significantly affect your options.
Can Bankruptcy Stop a Maryland Foreclosure?
In some circumstances, yes. Filing bankruptcy generally triggers an automatic stay that can temporarily stop foreclosure proceedings, including a scheduled auction. However, exceptions and limitations apply, and the bankruptcy court may allow the lender to proceed.
Chapter 13 bankruptcy may provide eligible homeowners with a structured way to address overdue mortgage payments while keeping up with ongoing obligations. Chapter 7 may temporarily delay foreclosure but generally does not provide the same repayment mechanism.
My recommendation: If foreclosure is approaching, speak with an experienced Maryland bankruptcy attorney before assuming that selling is your only option. An attorney can evaluate whether bankruptcy or another legal strategy may help in your specific circumstances.
Official Maryland Foreclosure Resources
For additional information about the legal process, homeowner rights, and available assistance:
Maryland Office of Financial Regulation
Maryland Courts — Foreclosure Information
Maryland People's Law Library — Foreclosure Steps
The Earlier You Explore Your Options, the Better.
Whether your goal is to keep your home, work out an agreement with your lender, or explore selling before foreclosure, understanding your choices is the next step. There may be more than one path forward, and the right solution depends on your individual circumstances.
This overview is for general educational purposes and is not legal, bankruptcy, or financial advice. Foreclosure procedures, deadlines, and eligibility requirements can vary. Consult a qualified Maryland attorney or HUD-approved housing counselor about your specific situation.
UNDERSTANDING YOUR OPTIONS
What Are Your Options to Avoid Foreclosure in Maryland?
If you're behind on mortgage payments or facing foreclosure, you may have several possible paths forward. Some involve working with your mortgage lender to keep your home. Others involve legal protections or selling the property before foreclosure.
The right option depends on your financial situation, mortgage balance, property value, and how much time you have. Not every solution is available to every homeowner, but understanding the possibilities is an important first step.
OPTION 01
Loan Modification
A loan modification changes certain terms of your existing mortgage. Depending on the loan and available programs, your mortgage servicer may consider adjustments intended to make the payments more manageable.
Who to contact: Your mortgage servicer or a HUD-approved housing counselor. Approval is not guaranteed, and any proposed terms should be reviewed carefully.
OPTION 02
Repayment Plans & Forbearance
If your financial hardship is temporary, your mortgage servicer may offer a repayment arrangement or forbearance. A repayment plan generally allows overdue amounts to be paid over time, while forbearance may temporarily reduce or suspend required payments.
Important: Forbearance usually does not erase missed payments. Ask your servicer how and when any postponed amounts must be repaid.
OPTION 03
Bankruptcy & Legal Protections
Bankruptcy may provide important legal protections for homeowners facing foreclosure. Filing bankruptcy generally triggers an automatic stay that can temporarily halt foreclosure proceedings, including an upcoming auction, subject to exceptions and limitations.
Chapter 13 may allow eligible homeowners to address overdue mortgage payments through a repayment plan while maintaining ongoing obligations. Chapter 7 may provide temporary relief but generally does not offer the same mechanism for catching up.
Who to contact: An experienced Maryland bankruptcy attorney. Bankruptcy does not guarantee that you can keep your home, and legal advice is especially important when a foreclosure sale is approaching.
OPTION 04
Sell Your Home Before Foreclosure
If your home is worth more than the mortgage balance and other amounts that must be paid at settlement, selling before foreclosure may allow you to pay off the debt and potentially walk away with remaining equity.
Depending on the home's condition, your timeline, and your priorities, you may be able to sell through traditional marketing or consider an as-is sale to a qualified buyer.
How I can help: Evaluate the property's market value, estimated selling expenses, mortgage payoff, and realistic sale timeline so you can make an informed decision.
OPTION 05
Short Sale
If you owe more on your mortgage and other required obligations than the property is likely to bring at sale, a short sale may be worth exploring. A short sale generally requires the mortgage lender or servicer to approve receiving less than the amount owed.
With more than 150 short sale transactions since 2007, I've helped homeowners navigate complicated property sales involving mortgage hardship, lender approval, and foreclosure concerns.
Important: Short sale approval is not guaranteed, and submitting a short sale request or listing the home does not automatically stop foreclosure. Any remaining debt, deficiency liability, or tax consequences should be reviewed with the appropriate professionals.
OPTION 06
Deed in Lieu of Foreclosure
A deed in lieu of foreclosure is an arrangement in which a homeowner voluntarily transfers ownership of the property to the lender, if the lender agrees to accept it, rather than completing the foreclosure process.
This may be an option in certain situations, particularly when keeping the home is no longer practical and other alternatives have not worked.
Important: Lender approval is required. Before signing anything, consult an attorney about potential remaining debt, junior liens, and other legal or financial consequences.
MY APPROACH
My Goal Isn't Necessarily to Sell Your House.
My goal is to help you understand your options. If keeping your home is possible, I want you to explore that. If selling is the better solution, I can help you understand what your property may be worth, what you owe, and what a realistic selling strategy could look like.
And if your situation calls for a foreclosure attorney, bankruptcy attorney, mortgage servicer, or housing counselor, those are the professionals who should guide you through those decisions.
Not Sure Which Option Makes Sense?
If you're considering selling your Maryland home because of mortgage difficulties, I'm happy to have a confidential, no-pressure conversation about your property's value, your timeline, and the real estate options that may be available.
Talk With Dan About Your Real Estate OptionsOr call/text 410-670-4762
Information provided for educational purposes only. Mortgage assistance programs, bankruptcy protections, short sales, and foreclosure alternatives depend on individual circumstances and eligibility. Dan McDevitt is a licensed Realtor, not an attorney, mortgage lender, financial adviser, or housing counselor. No foreclosure prevention outcome is guaranteed.
EXPERIENCE. GUIDANCE. REAL ESTATE SOLUTIONS.
How I Help Maryland Homeowners Facing Foreclosure
When you're facing mortgage difficulties, the last thing you need is someone pressuring you into a decision. You need accurate information, a realistic understanding of your property's value, and someone who knows how to navigate complicated real estate transactions.
I've been helping Maryland homeowners buy and sell real estate for more than 20 years, including navigating over 150 short-sale transactions since 2007. If selling your home is an option you're considering, here's how I can help you evaluate the situation and move forward.
01
We Start With a Conversation
First, I want to understand what's happening, what you're hoping to accomplish, and what concerns you most. Whether you've missed a few payments or have an upcoming foreclosure auction, we'll discuss your circumstances without judgment or pressure.
02
Evaluate Your Property & Equity
I'll evaluate the property's current market value, condition, comparable sales, and likely selling expenses. We'll also review the mortgage balance and other known obligations to estimate whether you may have equity or whether a short sale might need to be considered.
03
Explore Your Selling Options
Depending on your property and timeline, we can compare a traditional market sale, selling as-is, seeking competitive offers from local cash buyers, or pursuing a lender-approved short sale. I'll explain the potential benefits and tradeoffs so you can decide what makes sense.
04
Build a Realistic Strategy
If you decide to sell, we'll develop a strategy around your property's value, condition, buyer demand, and available time. When foreclosure is involved, pricing, preparation, marketing, and timing become especially important.
05
Handle Marketing & Negotiations
I'll coordinate the real estate side of the transaction, including property marketing, showings, buyer offers, negotiations, and communication with the appropriate professionals. If lender approval is required for a short sale, we'll coordinate the necessary process and documentation with the servicer and any authorized negotiator.
06
Coordinate the Path to Closing
From contract through settlement, I'll work with the buyer, title company, attorneys, lenders, and other parties as appropriate to address real estate transaction issues. My focus is helping you navigate the process with clear communication and realistic expectations.
ANOTHER OPTION WORTH UNDERSTANDING
You May Not Need to Repair or Clean Out Your Home Before Selling.
When someone is already dealing with mortgage problems, spending thousands of dollars on repairs or renovations may not be realistic. Depending on the property and market conditions, selling as-is may be worth considering.
I work with a network of local real estate investors and cash buyers who may be interested in properties that need repairs or updates. When appropriate, we can explore multiple offers and compare them with what the property might achieve through traditional marketing.
An important distinction: I'm a Realtor representing homeowners in real estate transactions, not an investor trying to purchase your property myself. My job is to help you evaluate your options and understand the terms, timing, and potential financial outcome of each offer.
What If a Foreclosure Auction Is Already Scheduled?
If a foreclosure sale date has already been scheduled, timing becomes critical. A property listing, purchase contract, or pending short sale does not automatically postpone foreclosure.
I can help evaluate whether a sale may be realistic within the available time, but homeowners should also speak promptly with a Maryland foreclosure attorney or bankruptcy attorney about their legal options. Any postponement or cancellation of a scheduled sale must be confirmed through the appropriate parties.
Let's Start by Understanding Your Situation.
You don't need to have all the answers before reaching out. If you're facing mortgage difficulties and considering selling your Maryland home, I'm happy to talk through your circumstances and help you understand the real estate options available.
Schedule a Confidential Conversation With DanPrefer to call or text? 410-670-4762
EXPERIENCE YOU CAN TURN TO
Meet Dan McDevitt
Helping Maryland homeowners navigate difficult real estate situations with experience, straightforward advice, and a practical understanding of the options available.
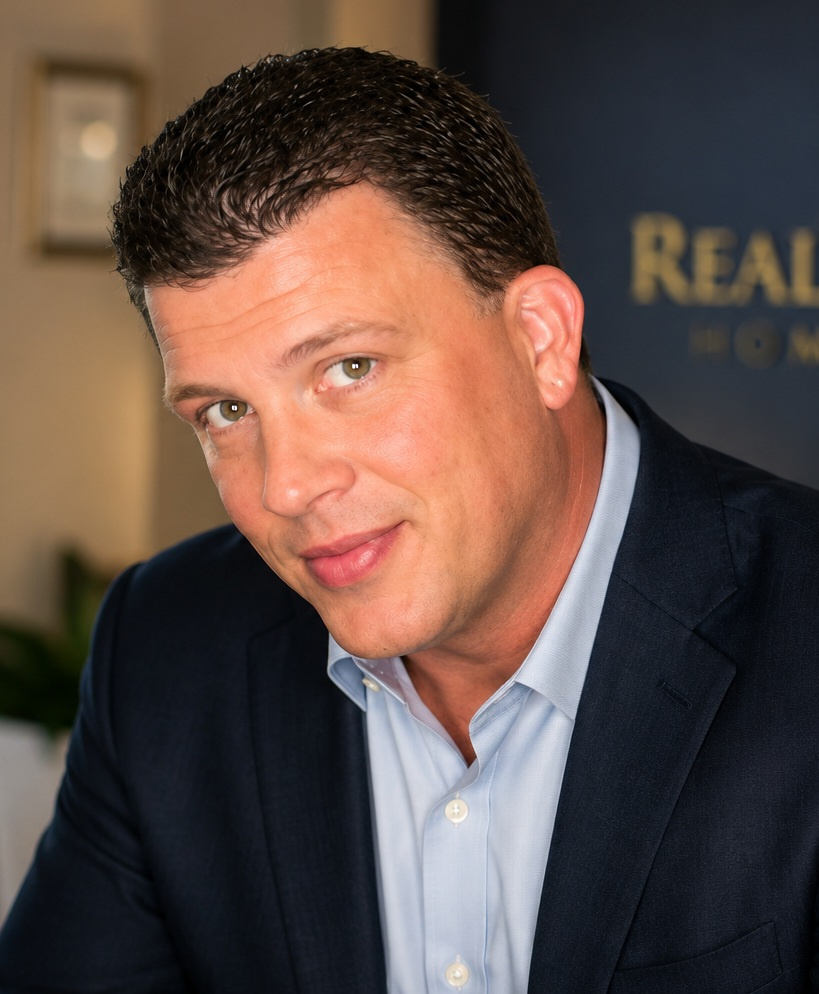
Dan McDevitt
President, RealVolution Homes Group
Realtor | Cummings & Company Realtors
Licensed in Maryland & Delaware
When Real Estate Gets Complicated, Experience Matters.
I'm Dan McDevitt, a Baltimore-area Realtor with Cummings & Company Realtors and President of RealVolution Homes Group. I've been helping homeowners buy and sell real estate for more than 20 years, and I'm licensed in both Maryland and Delaware.
Since 2007, I've worked through more than 150 short-sale transactions, helping homeowners navigate mortgage hardship, lender approvals, complicated property conditions, and time-sensitive sales.
My experience also includes probate and estate property sales, inherited homes, reverse mortgages, power of attorney transactions, divorce-related sales, bankruptcy-related property transactions, and homeowners facing foreclosure.
I understand that financial hardship can make an already difficult situation feel overwhelming. My approach is simple: listen, explain the real estate options honestly, and help you make an informed decision without pressure.
20+
Years of Real Estate Experience
150+
Short-Sale Transactions Since 2007
MD & DE
Licensed Real Estate Professional
You Deserve Straight Answers, Not More Pressure.
If you're behind on your mortgage, you may already be receiving calls, letters, and offers from people who want to buy your house. I understand why that can make it difficult to know whom to trust.
I'm not here to tell you that you have to sell. I'm here to help you understand what your property may be worth, what a sale could realistically accomplish, and whether selling fits your circumstances. If your best option involves working with your lender or consulting a foreclosure or bankruptcy attorney, I want you to explore that first.
Have Questions About Your Property?
If you're considering selling because of mortgage difficulties or an approaching foreclosure, let's have a conversation. I'll give you my perspective on the real estate side of your situation, and we'll take it from there.
Schedule a Conversation With DanCall or Text 410-670-4762
ANSWERS TO COMMON QUESTIONS
Maryland Foreclosure Prevention FAQs
If you're behind on your mortgage or facing foreclosure in Maryland, you probably have a lot of questions. Here are straightforward answers to some of the most common concerns homeowners have about foreclosure, bankruptcy, short sales, and selling a home before auction.
Can I sell my house if I'm behind on mortgage payments in Maryland?
Yes. Being behind on your mortgage does not automatically prevent you from selling your home. If the sale proceeds are sufficient to pay the mortgage, other required liens, and selling expenses, you may be able to complete a traditional sale and potentially retain remaining equity. If the proceeds will not cover the required payoff amounts, a lender-approved short sale may be an option. The available time and any scheduled foreclosure proceedings are important considerations.
What is a Notice of Intent to Foreclose in Maryland?
A Notice of Intent to Foreclose, commonly called an NOI, is a formal notice that a mortgage lender generally must send before initiating a residential mortgage foreclosure action in Maryland. Under Maryland's general rules, the notice must be sent at least 45 days before the foreclosure filing. Receiving an NOI does not mean your home has already been sold, but it is an important warning that you should review promptly. Contact your mortgage servicer and consider speaking with a housing counselor or attorney about available options.
How long does foreclosure take in Maryland?
There is no single timeline for every Maryland foreclosure. The process depends on state and federal requirements, the mortgage, court filings, loss mitigation reviews, mediation eligibility, and whether a sale is postponed or challenged. Maryland's general residential mortgage rules require certain notices and waiting periods before filing, and federal mortgage-servicing protections may also apply. Rather than assuming you have a particular number of months, review your actual notices and court documents with a qualified professional.
Can bankruptcy stop a foreclosure sale in Maryland?
In many situations, filing bankruptcy before a foreclosure auction triggers an automatic stay that temporarily stops foreclosure proceedings. However, exceptions and limitations apply, particularly in certain repeat-filing situations, and a lender may ask the bankruptcy court for permission to proceed. Chapter 13 may allow eligible homeowners to address overdue mortgage payments through a repayment plan while maintaining ongoing obligations. Chapter 7 may temporarily delay foreclosure but generally does not provide the same repayment mechanism. Bankruptcy does not guarantee that you can keep your home. If an auction is approaching, speak with an experienced Maryland bankruptcy attorney immediately.
Can I sell my Maryland home if a foreclosure auction is scheduled?
Potentially, yes, if the sale can be legally and practically completed before the foreclosure auction or if an authorized postponement creates sufficient time. However, simply listing the property or signing a purchase contract does not automatically stop the auction. If a sale date is approaching, contact a Maryland foreclosure attorney immediately and coordinate with your mortgage servicer. A Realtor can evaluate the property's market value, buyer demand, and whether a sale appears realistic within the available time.
What if I owe more than my home is worth?
If the property's likely sale proceeds are not enough to cover the mortgage and other required obligations, a short sale may be worth exploring. A short sale generally requires approval from the mortgage lender or servicer to accept less than the amount owed. With more than 150 short-sale transactions since 2007, I've helped homeowners navigate lender approvals and complicated sales. Approval is not guaranteed, and any potential remaining debt, deficiency liability, or tax consequences should be reviewed with qualified professionals.
Can I sell my home as-is before foreclosure?
Yes, an as-is sale may be an option depending on the property, market conditions, and available time. Selling as-is generally means the seller is not agreeing to make repairs, although required disclosures and contractual obligations may still apply. I work with local investors and cash buyers who may be interested in properties needing repairs, but I also evaluate traditional marketing opportunities. Comparing offers, closing timelines, and estimated net proceeds can help determine which approach makes sense.
Will listing my house or applying for a short sale stop foreclosure?
No, not automatically. Listing a property, receiving an offer, signing a contract, or submitting a short-sale application does not by itself stop or postpone a scheduled foreclosure auction. Depending on the circumstances, a lender may agree to postpone a sale, or certain legal protections may apply, but homeowners should never assume a postponement has occurred without confirmation from the appropriate parties. If an auction is scheduled, seek legal guidance promptly.
Can I keep my home if I've already received foreclosure papers?
Possibly. Receiving foreclosure documents does not necessarily mean every opportunity to keep your home has disappeared. Depending on your mortgage, financial circumstances, and stage of the proceedings, you may be able to explore loss mitigation, loan modification, reinstatement, mediation, or legal options such as Chapter 13 bankruptcy. Eligibility and deadlines matter. Contact your mortgage servicer and consider speaking with a HUD-approved housing counselor, foreclosure attorney, or bankruptcy attorney as soon as possible.
Who should I contact if I'm facing foreclosure in Maryland?
Start by contacting your mortgage servicer to understand your account status and available assistance programs. A HUD-approved housing counselor can help you review foreclosure prevention options. A Maryland foreclosure attorney can advise you about court proceedings and legal rights, while a bankruptcy attorney can evaluate whether bankruptcy protections may be appropriate. If selling your property is something you're considering, I can help you evaluate its market value, potential equity, and realistic selling options. You do not have to rely on just one professional for every aspect of the situation.
Still Have Questions About Your Situation?
Every foreclosure situation is different. If you're considering selling your home because of mortgage difficulties, I'm happy to help you understand what the property may be worth and what your real estate options could look like.
Ask Dan About Your Real Estate OptionsOr Call/Text 410-670-4762
These answers provide general educational information and are not legal, bankruptcy, mortgage, tax, or financial advice. Laws, deadlines, and available programs may change. Consult qualified professionals about your individual circumstances.
HELPFUL INFORMATION & SUPPORT
Maryland Foreclosure Prevention Resources
If you're facing foreclosure, you don't have to rely on one person or company for every answer. There are government agencies, nonprofit housing counselors, and legal professionals who can help you understand your rights and explore alternatives.
Maryland Homeowner Assistance
The Maryland Department of Housing and Community Development provides information about foreclosure prevention, housing counseling, and resources for homeowners experiencing mortgage difficulties.
Explore Maryland HOPE ResourcesHUD-Approved Housing Counseling
A HUD-approved housing counselor can help you understand mortgage assistance programs, communicate with your mortgage servicer, and evaluate possible foreclosure prevention options.
Find a HUD-Approved Housing CounselorMaryland Foreclosure Legal Information
The Maryland People's Law Library offers educational information about foreclosure proceedings, homeowner rights, and the legal process. A qualified Maryland attorney can provide advice specific to your situation.
Visit Maryland People's Law LibraryMaryland Foreclosure Regulations
The Maryland Office of Financial Regulation provides information about mortgage servicing, foreclosure requirements, consumer protections, and filing complaints involving regulated financial institutions.
Maryland Office of Financial RegulationBankruptcy & Legal Assistance
Bankruptcy may temporarily stop foreclosure through the automatic stay, subject to important exceptions. An experienced bankruptcy attorney can evaluate Chapter 7, Chapter 13, and other legal considerations. Maryland Legal Aid may also be a resource for eligible homeowners seeking legal assistance.
Explore Maryland Legal AidConsumer Financial Protection Bureau
The CFPB offers consumer information about mortgage hardship, working with mortgage servicers, avoiding foreclosure scams, and understanding mortgage assistance options.
Explore CFPB Foreclosure ResourcesRelated Maryland Real Estate Resources
Mortgage problems sometimes overlap with other complicated real estate situations. These additional resources may help you understand the options available for your property.
Reverse Mortgage Property Sales
Learn about selling a Maryland property with a reverse mortgage, including situations involving heirs, estates, and mortgage payoff complications.
Maryland Reverse Mortgage HelpProbate & Inherited Homes
Explore the real estate considerations involved when an inherited property or estate home has mortgage obligations or needs to be sold.
Maryland Probate & Estate Home SalesPower of Attorney & Senior Transitions
Understand the process of selling a parent's home using a power of attorney or managing a property sale during a senior living transition.
Maryland POA & Senior Home SalesLET'S TALK ABOUT YOUR OPTIONS
Facing Foreclosure in Maryland? You Don't Have to Figure Everything Out Alone.
If you're behind on mortgage payments, have received a foreclosure notice, or are considering selling your home before an auction, I'm happy to have a confidential conversation about the real estate side of your situation.
I'll help you understand what your property may be worth, whether you have equity, and what selling options might be realistic. If keeping your home is your goal, I encourage you to explore available lender assistance and speak with the appropriate housing or legal professionals.
Schedule a Free, Confidential ConversationCall or Text: 410-670-4762
Email: dan@realvolutionhomes.com
Dan McDevitt | RealVolution Homes Group
Cummings & Company Realtors
Serving Baltimore City, Baltimore County, Harford County, Anne Arundel County, Howard County, Cecil County, and surrounding Maryland communities.
The information on this page is intended for general educational purposes and does not constitute legal, bankruptcy, mortgage, tax, or financial advice. Dan McDevitt is a licensed real estate professional, not an attorney, lender, or housing counselor. Foreclosure deadlines, homeowner rights, and available assistance programs vary by circumstance. Listing or selling a property does not automatically postpone or stop foreclosure proceedings. Consult qualified professionals for guidance specific to your situation.